Choosing the right health insurance can be an important part of financial planning because medical treatment can become expensive without adequate coverage. The best health insurance policy is not necessarily the one with the lowest premium or the largest advertised coverage amount. A suitable policy should match a person’s healthcare needs, budget, age, family requirements, preferred hospitals, and expected medical expenses. Health insurance can help cover eligible hospitalization and treatment costs according to the terms and conditions of the policy. However, every plan has different features, exclusions, waiting periods, limits, and claim procedures. Understanding these details before purchasing coverage can help individuals and families make a more informed decision. This guide explains the major factors to consider when comparing health insurance policies and provides practical information for selecting coverage that fits different healthcare and financial situations.
What Is Health Insurance
Health insurance is a financial protection arrangement that can help cover eligible healthcare expenses according to the terms of an insurance contract. Depending on the policy, coverage may include hospitalization, certain day care procedures, pre and post hospitalization expenses, ambulance services, and other specified medical costs.
The policyholder generally pays a premium in exchange for the coverage provided by the insurer. When a covered medical event occurs, the insured person can submit a claim according to the policy’s procedures.
Health insurance can be purchased for an individual or a family. Different products are designed for different needs, so comparing policy features is important before making a decision.
Why Health Insurance Is Important
Medical expenses can increase quickly because of hospitalization, surgery, diagnostic tests, medicines, specialist consultations, and follow-up treatment.
Health insurance can reduce the financial burden of eligible expenses and provide greater predictability when unexpected healthcare needs arise.
For families, insurance can be particularly useful because several members may require medical treatment at different times. A suitable policy can provide financial support while allowing households to plan their other expenses more effectively.
Health insurance can also encourage people to seek timely medical attention instead of postponing necessary treatment because of concerns about immediate costs.
Types of Health Insurance Policies
There are several common types of health insurance coverage. Individual health insurance generally provides coverage for one insured person.
Family floater plans can cover multiple family members under a shared sum insured. These plans may be useful for families because the available coverage can be used by different members according to the policy terms.
Senior citizen health insurance is designed for older adults and may have features specifically related to their healthcare requirements.
Group health insurance is often provided by employers to employees. Although employer-sponsored coverage can be useful, employees may also consider whether additional personal insurance is appropriate for their circumstances.
Specific policies may also focus on particular illnesses, critical conditions, maternity requirements, or other specialized healthcare needs.
Understanding Sum Insured
The sum insured is one of the most important features to evaluate. It represents the maximum amount available for covered expenses during the policy period, subject to the policy’s terms and limits.
A suitable coverage amount depends on several factors, including age, location, family size, healthcare costs, existing medical conditions, and expected future needs.
Choosing a very low sum insured simply to reduce the premium may leave a policyholder underinsured when significant medical treatment is required.
At the same time, selecting an unnecessarily large amount without considering affordability may make long-term premium payments difficult.
The goal should be to choose a sustainable level of coverage that provides meaningful financial protection.
Hospitalization Coverage
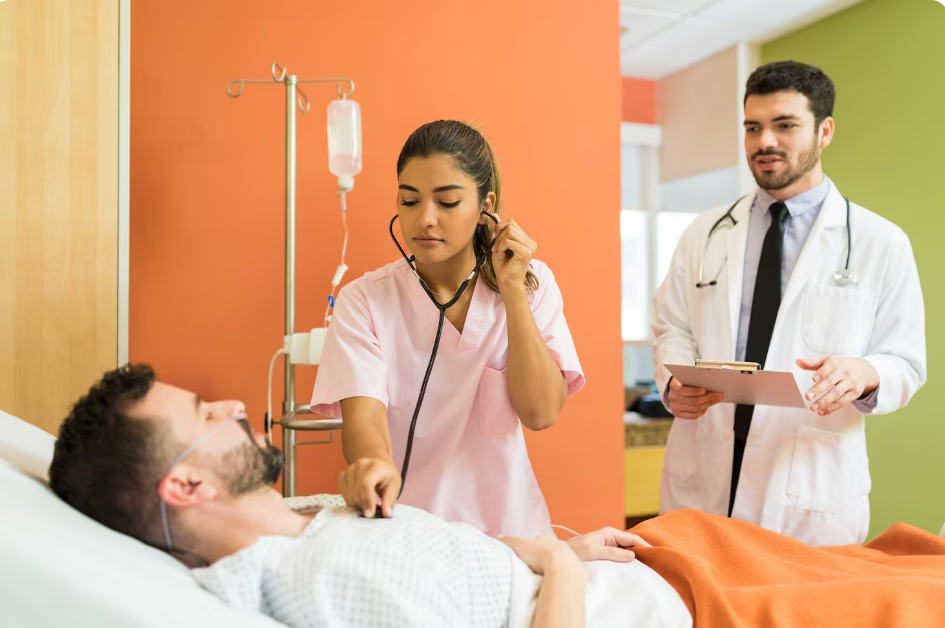
Hospitalization coverage is a central feature of many health insurance policies. It can cover eligible expenses associated with hospitalization when the policy conditions are satisfied.
Coverage can differ significantly between plans. Some policies may have room-rent limits, sub-limits, deductibles, co-payments, or other restrictions.
Before purchasing a plan, it is important to understand what hospitalization expenses are covered and what expenses may remain the policyholder’s responsibility.
Reading the policy wording carefully can help avoid misunderstandings during a claim.
Cashless Hospitalization
Cashless hospitalization can make the claims process more convenient when treatment is received at an eligible network hospital.
Instead of paying the entire eligible bill upfront and seeking reimbursement later, the insurer or its claims administrator may settle eligible expenses directly with the network hospital according to the policy terms.
However, cashless treatment does not necessarily mean that every expense is covered. Non-covered items, deductibles, co-payments, exclusions, or expenses exceeding applicable limits may still need to be paid by the patient.
Therefore, policyholders should understand both the cashless process and the network hospital conditions.
Waiting Periods
Waiting periods are an important factor that is sometimes overlooked when buying insurance.
Certain treatments or medical conditions may have waiting periods before coverage becomes available. Pre-existing diseases can also be subject to specific waiting periods depending on the policy.
Some policies may have separate waiting periods for particular procedures or conditions.
When comparing plans, consumers should examine these periods carefully rather than focusing only on the premium.
A policy with a slightly higher premium but more suitable waiting-period conditions may be more practical for someone with immediate or expected healthcare requirements.
Pre-Existing Diseases
A pre-existing disease generally refers to a medical condition that existed before purchasing the insurance policy, according to the insurer’s policy definition.
Coverage for such conditions may be subject to underwriting requirements and waiting periods.
Applicants should provide accurate information about their medical history. Failure to disclose relevant information can create complications during the claims process.
People with existing health conditions should pay particular attention to waiting periods, exclusions, coverage limits, medical examinations, and policy renewal conditions.
Room Rent and Other Limits
Some health insurance policies include limits on room rent or specific categories of hospital accommodation.
A room-rent restriction can indirectly affect the amount payable for certain associated hospital expenses, depending on the policy structure.
Policies may also contain sub-limits for specific treatments or services.
Consumers should therefore look beyond the headline sum insured and examine the internal limits that may influence the actual claim amount.
A policy with a large advertised coverage amount may still have important restrictions that should be understood before purchase.
Co-Payment and Deductibles
Co-payment means that the insured person is required to pay a specified portion of an eligible medical expense, while the insurer pays the remaining amount according to the policy.
A deductible is an amount that must be paid by the policyholder before the insurance coverage begins to contribute, depending on the policy structure.
These features can sometimes reduce premiums, but they can also increase the individual’s financial responsibility during a claim.
Anyone comparing policies should calculate the possible out-of-pocket cost rather than looking at the premium alone.
Network Hospitals
The availability of network hospitals can be an important consideration when choosing health insurance.
People should check whether hospitals they are likely to use are included in the insurer’s network. Location also matters. A broad network can be useful for individuals who travel frequently or live in areas where healthcare facilities are spread across different locations.
Hospital networks can change over time, so policyholders should verify current network information when treatment is required.
Premium and Long-Term Affordability
Premium is an important factor, but it should not be the only basis for choosing a policy.
Health insurance is generally intended to provide protection over the long term. A policy should therefore be affordable enough to maintain through future renewals.
Premiums can vary according to age, coverage amount, location, medical history, policy type, and other factors.
When comparing plans, consider the total financial commitment over several years rather than focusing only on the first year’s premium.
Claim Settlement and Customer Service
The claims process is an important part of the insurance experience. Policyholders should understand how claims are reported, which documents may be required, and how reimbursement or cashless procedures work.
Customer service can also matter when policyholders need clarification about coverage, documentation, hospital networks, or renewal.
Rather than relying only on promotional claims, consumers can examine policy documents, claim procedures, service terms, and available information from reliable sources.
Renewal and Lifetime Coverage
Long-term health insurance planning requires attention to renewal conditions.
Policyholders should understand renewal rules, premium changes, continuity benefits, and whether coverage can continue as the insured person becomes older.
Maintaining continuous coverage can be particularly important because changing insurers later may involve new waiting periods or underwriting considerations.
People should review their coverage periodically and consider whether the sum insured remains appropriate as healthcare costs and family circumstances change.
How to Compare Health Insurance Policies
A practical comparison should begin with coverage requirements. Consider who needs insurance, expected medical needs, family size, age, and existing conditions.
Next, compare the sum insured and major benefits. Then examine waiting periods, exclusions, room-rent restrictions, co-payments, deductibles, and sub-limits.
Network hospitals should also be checked, particularly those located near home or work.
Finally, compare premiums, renewal conditions, claim procedures, customer service, and other important policy terms.
This approach can provide a more complete picture than comparing premiums alone.
Common Mistakes to Avoid
One common mistake is selecting insurance solely because it has a low premium. A cheaper plan may have limitations that reduce its usefulness.
Another mistake is choosing insufficient coverage because the policy appears affordable at the time of purchase.
Ignoring pre-existing disease conditions, waiting periods, exclusions, and co-payments can also create problems later.
Some buyers may also fail to update their coverage after major life changes such as marriage, childbirth, relocation, or changes in income.
Reading the policy documents and asking questions before purchasing can help reduce these risks.
Key Points to Remember
Health insurance can provide financial protection against eligible medical expenses.
The right coverage amount depends on personal and family healthcare needs.
Premium should not be the only factor when comparing policies.
Waiting periods and exclusions should be understood before purchasing.
Room-rent limits, co-payments, deductibles, and sub-limits can affect out-of-pocket expenses.
Network hospitals can make cashless treatment more convenient.
Existing medical conditions should be disclosed accurately.
Long-term affordability is important because health insurance is generally intended for continued coverage.
Tips for Choosing Health Insurance
Start by estimating your likely healthcare needs rather than selecting a policy based only on advertisements or premium prices.
Compare several policies using the same criteria, including sum insured, hospitalization coverage, waiting periods, exclusions, network hospitals, deductibles, co-payments, and renewal terms.
Read the policy wording and related documents carefully before purchasing. If a term is unclear, ask the insurer or an appropriately qualified insurance professional for clarification.
Consider whether the coverage will remain adequate as your family grows or healthcare costs increase.
Keep copies of policy documents, premium receipts, medical records, and claim-related paperwork in an organized place.
Review your insurance periodically. Your financial situation and healthcare requirements may change, so the coverage that was suitable several years ago may not remain appropriate.
Final Thoughts
Choosing health insurance is an important financial decision that should be based on coverage needs, affordability, policy conditions, and long-term requirements. The best health insurance policy for one person may not be suitable for another because age, family size, medical history, location, budget, and healthcare expectations differ. A careful comparison should include the sum insured, hospitalization benefits, waiting periods, exclusions, network hospitals, co-payments, deductibles, claim procedures, and renewal conditions. Instead of focusing on a single feature, consumers can evaluate the overall protection and potential out-of-pocket expenses offered by each policy. Taking time to understand the policy before purchasing can help individuals and families make more informed decisions about their healthcare finances.
Frequently Asked Questions
1. What should I look for in a health insurance policy?
Look at the sum insured, hospitalization coverage, waiting periods, exclusions, network hospitals, room-rent limits, co-payments, deductibles, claim procedures, renewal conditions, and premium affordability.
2. Is a higher sum insured always better?
Not necessarily. A higher sum insured can provide greater potential financial protection, but affordability and the policy’s terms also matter. The appropriate amount depends on individual healthcare requirements and financial circumstances.
3. Why are waiting periods important?
Waiting periods determine how long a policyholder may need to wait before certain conditions or treatments become eligible for coverage. The applicable periods vary between policies.
4. What is a family floater health insurance plan?
A family floater plan provides a shared sum insured for multiple covered family members. The available coverage can generally be used by different members according to the policy terms.
5. Can health insurance cover pre-existing diseases?
Pre-existing diseases may be covered subject to the policy’s terms, applicable waiting periods, underwriting requirements, and disclosure conditions. Policyholders should provide accurate medical information when applying for coverage.